Page 9 of 10 FirstFirst ... 7 8 9 10 LastLast
Results 81 to 90 of 92
Like Tree1Likes

Daily Market Analysis from HFM

This is a discussion on Daily Market Analysis from HFM within the Analytics and News forums, part of the Trading Forum category; Date: 21st August 2026. Gold Rises as Treasury Yields Rebound and Walmart Pressures the NASDAQ. Trading Leveraged products is Risky ...


  1. #81
    Junior Member HFblogNews's Avatar
    Join Date
    Nov 2021
    Posts
    99
    Date: 21st August 2026.

    Gold Rises as Treasury Yields Rebound and Walmart Pressures the NASDAQ.


    Trading Leveraged products is Risky

    Scott Bessent continues to support the Treasury’s move to buy back long-term bonds and has indicated larger future buybacks. The bond market did see yields decline after the Treasury announced its ‘new strategy’. However, yields are quickly rebounding, indicating that the US government may struggle to beat bond vigilantes.

    On Friday, the trend of the past 48 hours continues with the stock market and the US Dollar declining and Gold rising. Investors are looking to determine how to change their price targets based on the changing market conditions and fundamentals.


    HFM - US Dollar 4-Hour Chart

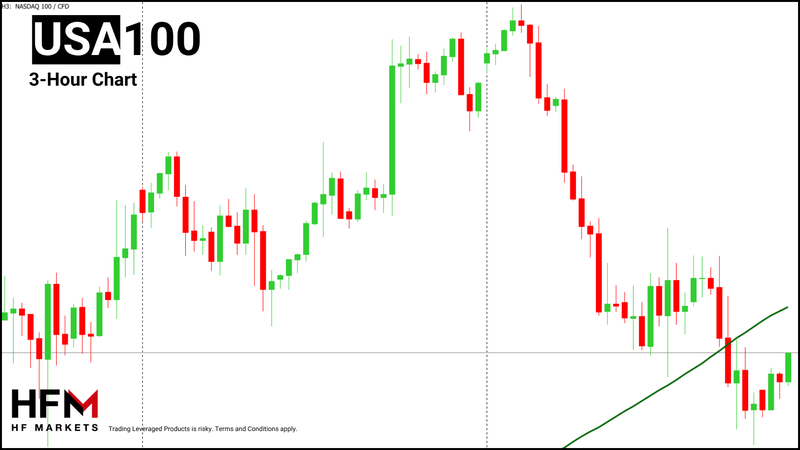
    In terms of technical analysis, the NASDAQ is trading above the 200-bar moving average on the 5-minute chart. However, the moving average continues to trade lower, and moving averages indicate bearish price movement on all other timeframes. Component analysis on Thursday indicated bearish price movement. This is due to 69% of the most influential components declining and the most volatile stocks falling, not increasing. However, the VIX index is trading slightly higher this morning, which may point to a retracement.

    If the price rises above $29,397, buy signals can materialise as the price rises above a key trendline and away from the VWAP. A move above this price can indicate a daily correction. However, if the price regains bearish momentum, dropping below $29,206, sell signals remain intact.

    Gold Maintains Bullish Indications

    Gold remains technically bullish after breaking above the key $4,500 psychological level, which now acts as an important support zone. As long as XAU/USD holds above $–$4,470, buyers remain in control, with resistance at $4,565, followed by $4,580 and $4,610. Currently, gold is being supported by investors fearing instability, government debt, and a possible recession.

    Momentum remains strong but increasingly stretched after the recent rally, raising the risk of short-term profit-taking. A break above $4,560 could extend gains towards $4,600, while a move back below $4,500 could trigger a deeper correction towards $4,470–$4,450. If inflation or oil prices rise, Gold may again come under pressure from rate-hike expectations.

    EURUSD - Dollar Weakness and ECB Rate Hike Support The Euro

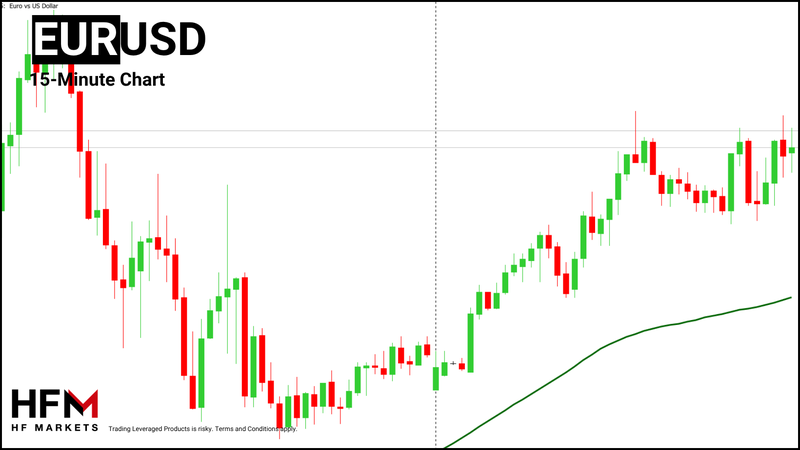
    One of the best-performing currencies this week has been the Euro which has found support from Dollar weakness and expectations of an ECB September rate hike. The EUR/USD remains technically bullish, trading close to 1.1670–1.1700 as continued US Dollar weakness supports the pair. Immediate resistance is at 1.1700, followed by 1.1750; a sustained break above 1.1700 could strengthen the bullish trend and potentially open the way towards higher levels.

    On the downside, 1.1650 is the first important support, followed by 1.1600-1.1550. As long as EUR/USD remains above this zone, buyers retain the advantage, while a break below 1.1550 would weaken the current bullish structure. This could increase the risk of a deeper correction.


    HFM - EURUSD 15-Minute Chart

    According to Scott Bessent, the US Treasury Secretary, the Dollar’s decline over the past two days is purely market noise. While Bessent was speaking with journalists, he advised that the markets will soon see the Treasury’s intentions and that volatility will normalise.

    Key Takeaways:

    * US Treasury bond buybacks pushed yields lower initially, but yields are rebounding, showing that pressure in the bond market remains.
    * Walmart shares fell 9% despite solid headline earnings, as comparable sales missed expectations and raised concerns about consumer strength.
    * The NASDAQ remains under pressure from inflation concerns, higher oil prices, rate-hike expectations, and fiscal risks.
    * Gold remains technically bullish above $4,500, supported by concerns over debt, instability, and recession risks.
    * EUR/USD remains bullish, supported by US Dollar weakness and expectations of a possible ECB rate hike.

    Always trade with strict risk management. Your capital is the single most important aspect of your trading business.

    Please note that times displayed based on local time zone and are from time of writing this report.

    Click HERE to access the full HFM Economic calendar.

    Want to learn to trade and analyse the markets? Join our webinars and get analysis and trading ideas combined with better understanding of how markets work. Click HERE to register for FREE!

    Click HERE to READ more Market news.

    Michalis Efthymiou
    HFMarkets


    Disclaimer: This material is provided as a general marketing communication for information purposes only and does not constitute an independent investment research. Nothing in this communication contains, or should be considered as containing, an investment advice or an investment recommendation or a solicitation for the purpose of buying or selling of any financial instrument. All information provided is gathered from reputable sources and any information containing an indication of past performance is not a guarantee or reliable indicator of future performance. Users acknowledge that any investment in Leveraged Products is characterized by a certain degree of uncertainty and that any investment of this nature involves a high level of risk for which the users are solely responsible and liable. We assume no liability for any loss arising from any investment made based on the information provided in this communication. This communication must not be reproduced or further distributed without our prior written permission.
  2. #82
    Junior Member HFblogNews's Avatar
    Join Date
    Nov 2021
    Posts
    99
    Date: 24th August 2026.

    Market Outlook Today: Gold Rallies as Oil and Asian Stocks Fall.


    Trading Leveraged products is Risky

    Today’s market outlook is dominated by geopolitical tension, US fiscal concerns, and uncertainty ahead of several major events. Gold reached a three-month high overnight, while oil prices and Asian stocks declined as traders awaited details of new US sanctions against Iran.

    Attention will later shift towards NVIDIA’s earnings, US inflation data, and Federal Reserve Chair Kevin Warsh’s Jackson Hole speech. Together, these events could drive volatility across commodities, currencies, bonds, and global stock markets.

    Key takeaways

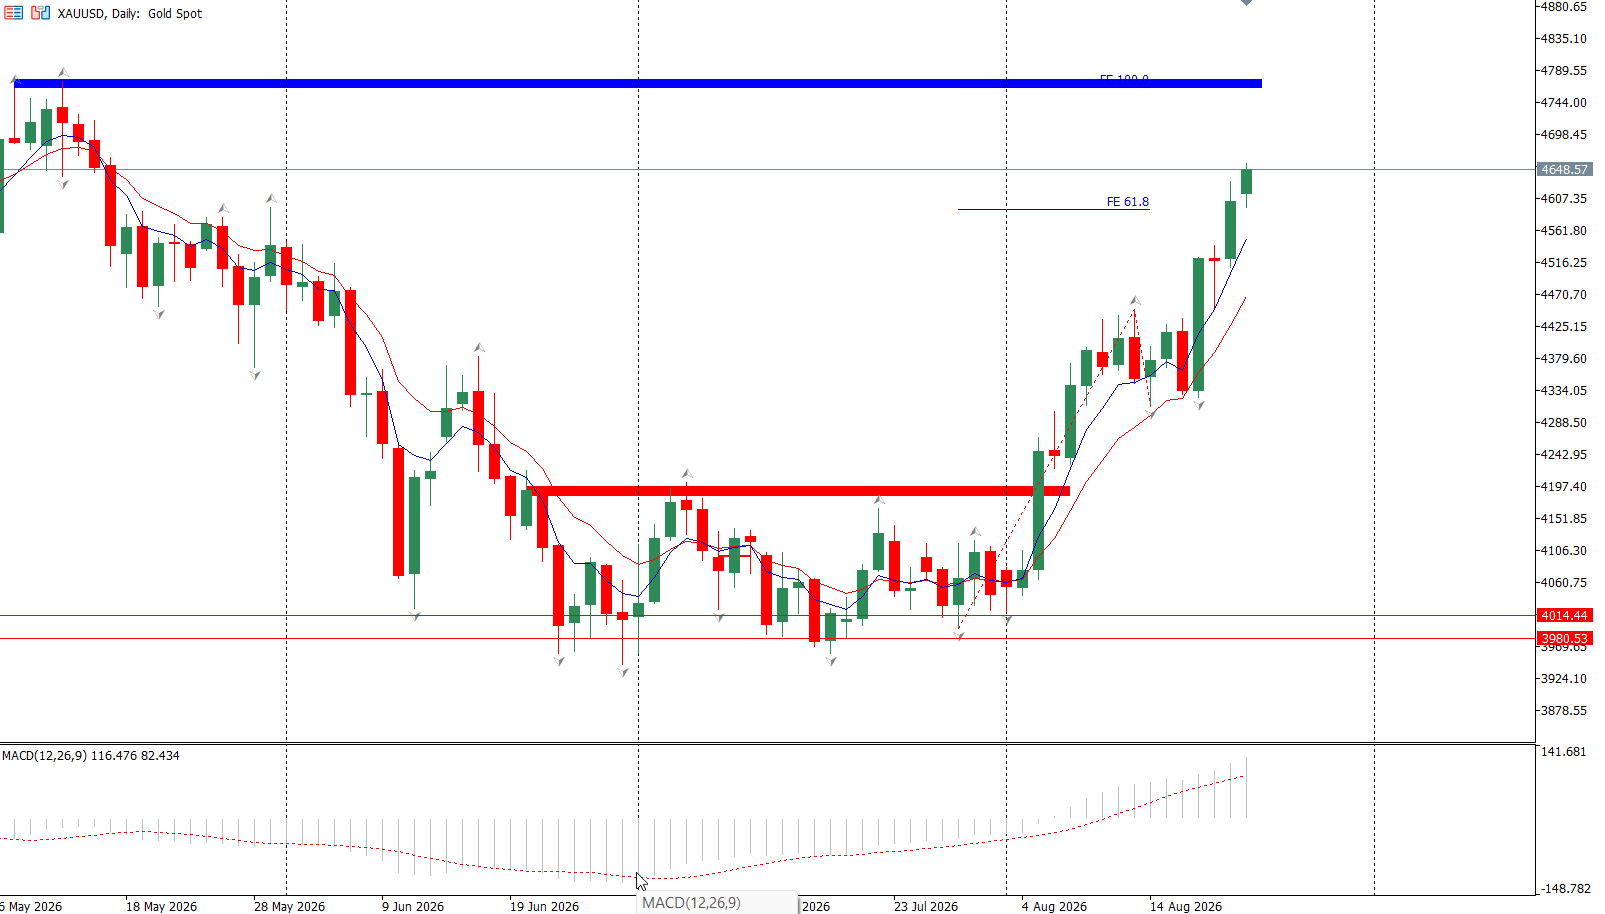
    * Gold climbed above $4,640 as concerns about US debt and dollar weakness increased demand for alternative assets.
    * Oil fell by around 2% due to profit-taking, but risks surrounding Iran and the Strait of Hormuz remain elevated.
    * Asian stocks declined, led by sharp losses in Samsung, Alibaba, and other technology-related companies.
    * NVIDIA’s earnings on Wednesday could determine whether the AI-driven stock market rally can continue.
    * Traders will monitor Iran sanctions, US inflation, and Jackson Hole for their potential impact on interest rate expectations.

    Asian Stocks Fall as Technology Concerns Increase

    Asian equity markets traded lower overnight. The MSCI Asia-Pacific index outside Japan fell around 0.9%, while South Korean technology shares came under particular pressure. Japan’s Nikkei remained close to unchanged after losing almost 4% last week.

    Samsung Electronics fell 7.5% as investors reacted negatively to its plans to return capital to shareholders. Alibaba dropped 9.7% after announcing a $10.2 billion share sale to finance its expansion in artificial intelligence. SoftBank also declined after revealing plans for a record retail bond offering in Japan.

    These developments highlight a change in the AI investment narrative. Investors are no longer focusing only on how much companies are spending on AI. They increasingly want evidence that these investments can generate sustainable revenue and attractive returns.

    European and US equity futures were relatively stable during the Asian session, indicating that many investors are avoiding large positions ahead of this week’s major events.

    NVIDIA Earnings Could Determine the Direction of Technology Stocks

    Nvidia will report its quarterly results on Wednesday, making the announcement one of the most important events of the week for global stock markets.

    Analysts expect the chipmaker’s quarterly revenue to almost double to approximately $92 billion. However, these high expectations create considerable risk if revenue, profit margins or forward guidance disappoint.

    Investors will also examine the effect of Nvidia’s reported price increases on customer demand. Rising hardware costs may reduce the potential returns of companies already investing heavily in AI infrastructure.

    Strong results and guidance could revive demand for technology and semiconductor stocks. A disappointment, however, may reinforce concerns about expensive valuations and the sustainability of the AI-led rally.


    Oil Prices Fall, but Iran Risks Remain Elevated

    Oil prices declined by around 2% during early Asian trading as traders took profits following last week’s gains of more than 5%.

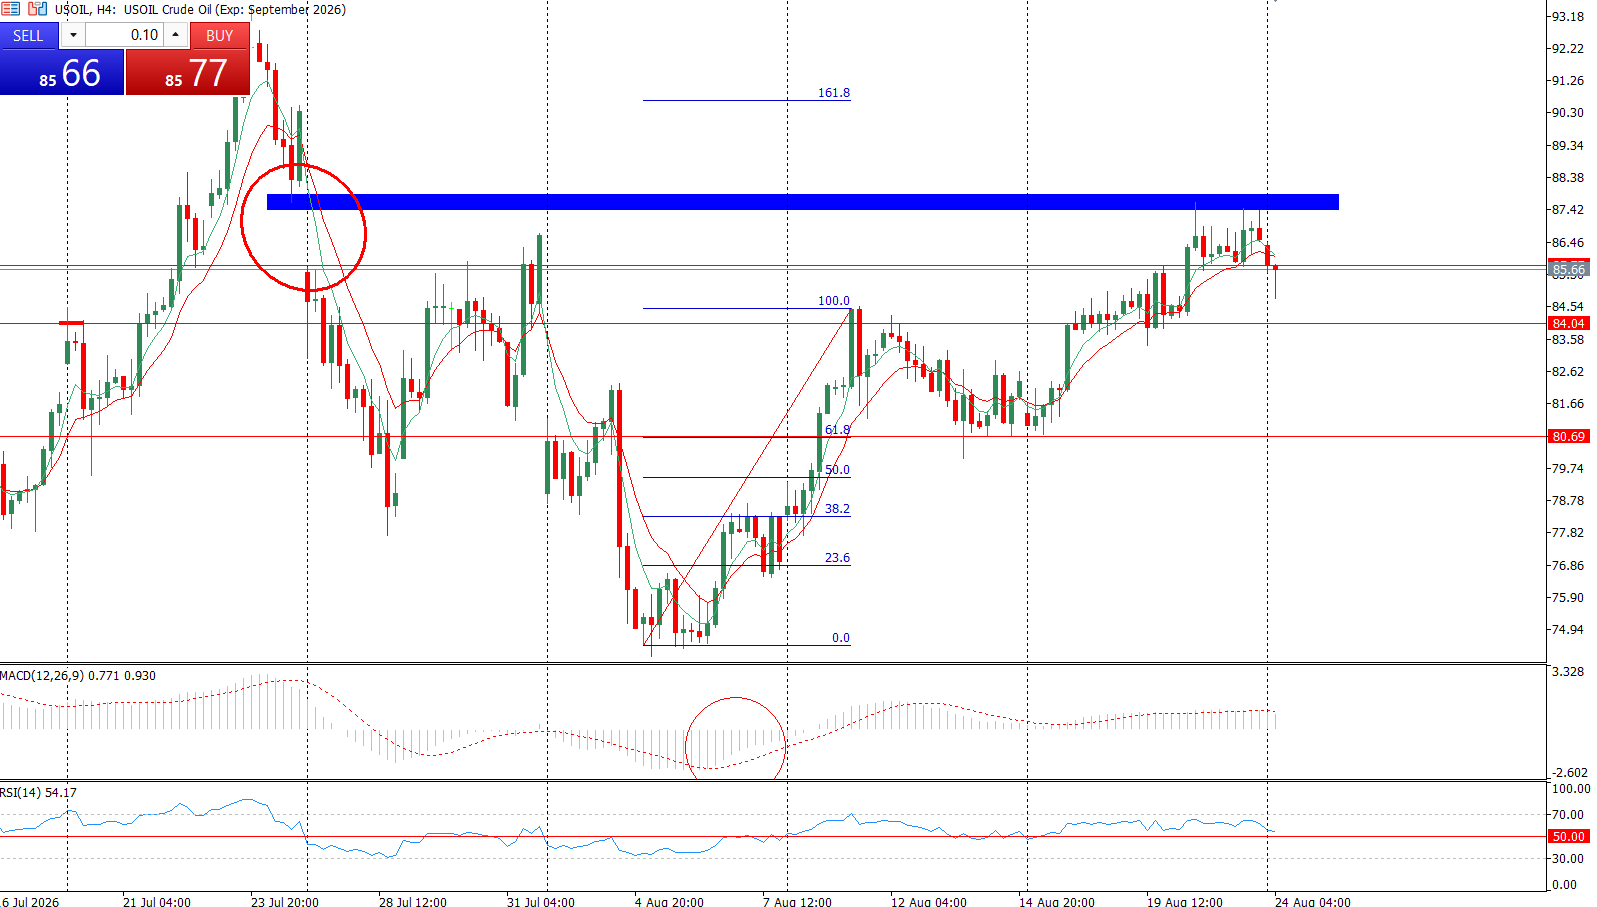
    Brent crude moved towards $93 per barrel, while WTI traded close to $85. The decline does not necessarily indicate an improvement in the geopolitical situation. Instead, traders appear to be reducing positions before the US announces its latest economic measures against Iran.

    The new sanctions are expected to target entities involved in buying and transporting Iranian oil, processing the country’s financial transactions and supporting transfers of fuel at sea.

    If the measures discourage buyers, banks and shipping companies from handling Iranian crude, global oil supplies could tighten further. Iran has also warned that participation in the US economic campaign may be treated as an act of war.

    Diplomatic efforts have not completely disappeared, with Pakistan attempting to encourage renewed negotiations between Washington and Tehran. Meanwhile, the absence of confirmed attacks in the Strait of Hormuz over the past 48 hours has reduced some immediate pressure on oil prices.

    For traders, the key issue is whether the sanctions will materially reduce Iranian exports or provoke another escalation in the region.


    Gold Reaches Its Highest Level in Three Months

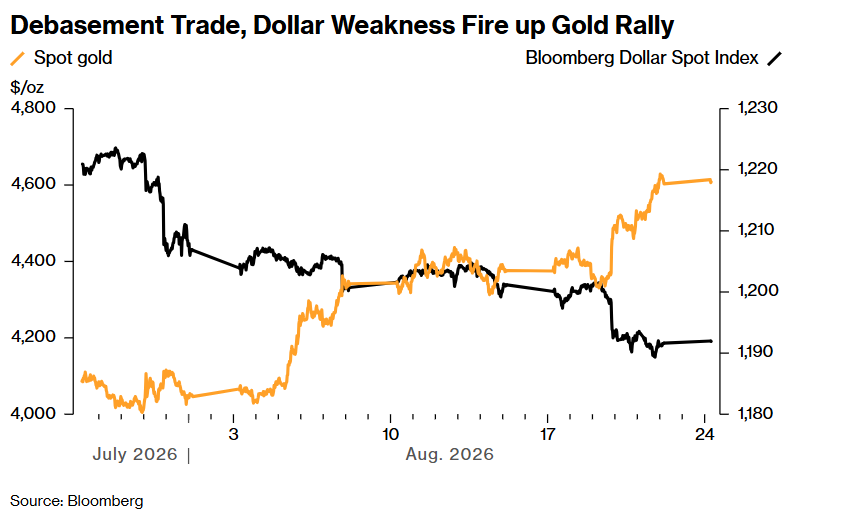
    Gold extended its rally above $4,640 per ounce, reaching its highest level since May. The precious metal gained more than 5% last week and has risen over 15% so far in August.

    The rally is being supported by concerns over US debt, fiscal policy and the dollar’s long-term purchasing power. The Treasury’s decision to increase buybacks of longer-dated government bonds initially pushed yields and the dollar lower, making gold more attractive.

    Hedge funds have also increased their bearish positions on the US dollar, while institutional demand for protection against further dollar weakness has grown. Gold-backed exchange-traded funds recorded their strongest weekly inflows since January, indicating broader participation in the rally.

    Nevertheless, gold’s rapid advance creates the possibility of short-term profit-taking. A recovery in the US dollar or real bond yields would be among the main risks to its bullish momentum.


    US Bond Yields Remain a Concern for Stock Markets

    Despite the Treasury’s intervention, long-term US borrowing costs remain elevated. The 30-year Treasury yield is above 5.25%, close to its highest level in 19 years, while the 10-year yield is trading near 4.71%.

    Higher yields can pressure stocks by making government bonds more attractive. They also reduce the present value of companies’ future earnings, creating a particular challenge for highly valued technology shares.

    Traders will therefore assess whether Treasury Secretary Scott Bessent presents a credible fiscal plan for addressing government borrowing and rising debt. Increased bond buybacks may temporarily support the market, but concerns could continue without meaningful progress on budget deficits.

    US Dollar Remains Under Pressure

    The US Dollar Index is trading near 96.80 after falling approximately 0.8% last week. Investors are concerned that greater government involvement in the Treasury market could weaken confidence in the currency.

    The euro held close to $1.1680, while USDJPY traded around 158.90.

    The Canadian dollar weakened against the greenback after trade negotiations between the US and Canada collapsed. Canada announced retaliatory tariffs covering US steel, dairy products, electronics, agricultural equipment and other goods.

    The dispute could increase inflationary pressure and create further volatility in USDCAD.

    What Should Traders Watch Today?

    The main event today will be the announcement detailing the new US sanctions against Iran. Traders should focus on whether the measures directly affect oil buyers, banks, shipping companies or countries helping Tehran maintain its exports.

    Stricter sanctions could lift oil prices and inflation expectations. This may push bond yields higher, pressure stock markets and create a more complicated environment for gold. The precious metal could benefit from geopolitical uncertainty but may face resistance if real yields rise sharply.

    Later this week, attention will turn to:

    * Nvidia’s earnings on Wednesday
    * US inflation figures
    * Federal Reserve Chair Kevin Warsh’s Jackson Hole speech on Friday
    * Further developments in the US-Canada trade dispute
    * Oil flows and tanker activity around the Strait of Hormuz

    Markets currently indicate approximately a 40% probability of a Federal Reserve rate hike in September, with a move fully priced by December. These expectations could change if inflation remains elevated or the Fed Chair signals that interest rates may need to remain higher.

    Market Outlook for the Rest of the Day

    The market outlook today remains highly dependent on political and economic headlines. Oil could react sharply to the details of the Iran sanctions, while gold may remain supported by dollar weakness and concerns surrounding US fiscal policy.

    Stock market activity may remain cautious before Nvidia’s earnings and the Jackson Hole gathering. Traders should prepare for sudden price movements, monitor bond yields and avoid assuming that Monday’s relatively quiet opening means volatility has disappeared.

    Always trade with strict risk management. Your capital is the single most important aspect of your trading business.

    Please note that times displayed based on local time zone and are from time of writing this report.

    Click HERE to access the full HFM Economic calendar.

    Want to learn to trade and analyse the markets? Join our webinars and get analysis and trading ideas combined with better understanding of how markets work. Click HERE to register for FREE!

    Click HERE to READ more Market news.

    Andria Pichidi
    HFMarkets


    Disclaimer: This material is provided as a general marketing communication for information purposes only and does not constitute an independent investment research. Nothing in this communication contains, or should be considered as containing, an investment advice or an investment recommendation or a solicitation for the purpose of buying or selling of any financial instrument. All information provided is gathered from reputable sources and any information containing an indication of past performance is not a guarantee or reliable indicator of future performance. Users acknowledge that any investment in Leveraged Products is characterized by a certain degree of uncertainty and that any investment of this nature involves a high level of risk for which the users are solely responsible and liable. We assume no liability for any loss arising from any investment made based on the information provided in this communication. This communication must not be reproduced or further distributed without our prior written permission.

  3. #83
    Junior Member HFblogNews's Avatar
    Join Date
    Nov 2021
    Posts
    99
    Date: 25th August 2026.

    Markets Stabilise Ahead of NVIDIA Earnings as Bitcoin Breaks Above $80,000.


    Trading Leveraged products is Risky

    US stock index futures moved higher on Tuesday as selling pressure across the technology sector began to ease. However, with NVIDIA earnings, the Jackson Hole symposium, and geopolitical risks all in focus, volatility may remain elevated across stocks, currencies, commodities, and cryptocurrencies.

    NASDAQ 100 futures gained approximately 0.4% after the technology-heavy index came under pressure during Monday’s session. The decline was driven largely by semiconductor stocks, with investors reducing exposure before NVIDIA releases its quarterly results on Wednesday.

    Asian markets delivered a mixed performance, although the broader MSCI Asia Pacific Index recovered from earlier losses. European equity markets were also positioned for a positive opening, suggesting that risk sentiment had improved slightly.

    Nevertheless, the recovery remains cautious rather than decisive.

    NVIDIA Earnings Could Set the Direction for Technology Stocks

    NVIDIA has become one of the most important indicators of investor confidence in the artificial intelligence sector. Its shares fell 2.9% on Monday, extending their longest losing streak since 2022, while Micron Technology and Broadcom also recorded notable declines.

    The weakness reflects growing concerns that valuations across the semiconductor sector may have moved too far ahead of underlying earnings growth.

    NVIDIA’s upcoming results will therefore be examined for evidence that demand for AI infrastructure remains strong. Traders are likely to focus on revenue growth, data centre demand, profit margins, and management’s forward guidance.

    Strong results and an optimistic outlook could revive demand for semiconductor and technology shares. However, disappointing guidance may reinforce concerns that the AI investment cycle is slowing, potentially placing further pressure on the NASDAQ 100 and S&P 500.

    This makes NVIDIA’s announcement more than an individual corporate event. It could influence sentiment across the entire AI trade and determine whether the recent weakness in technology stocks develops into a broader correction.

    Bitcoin Breaks Through $80,000

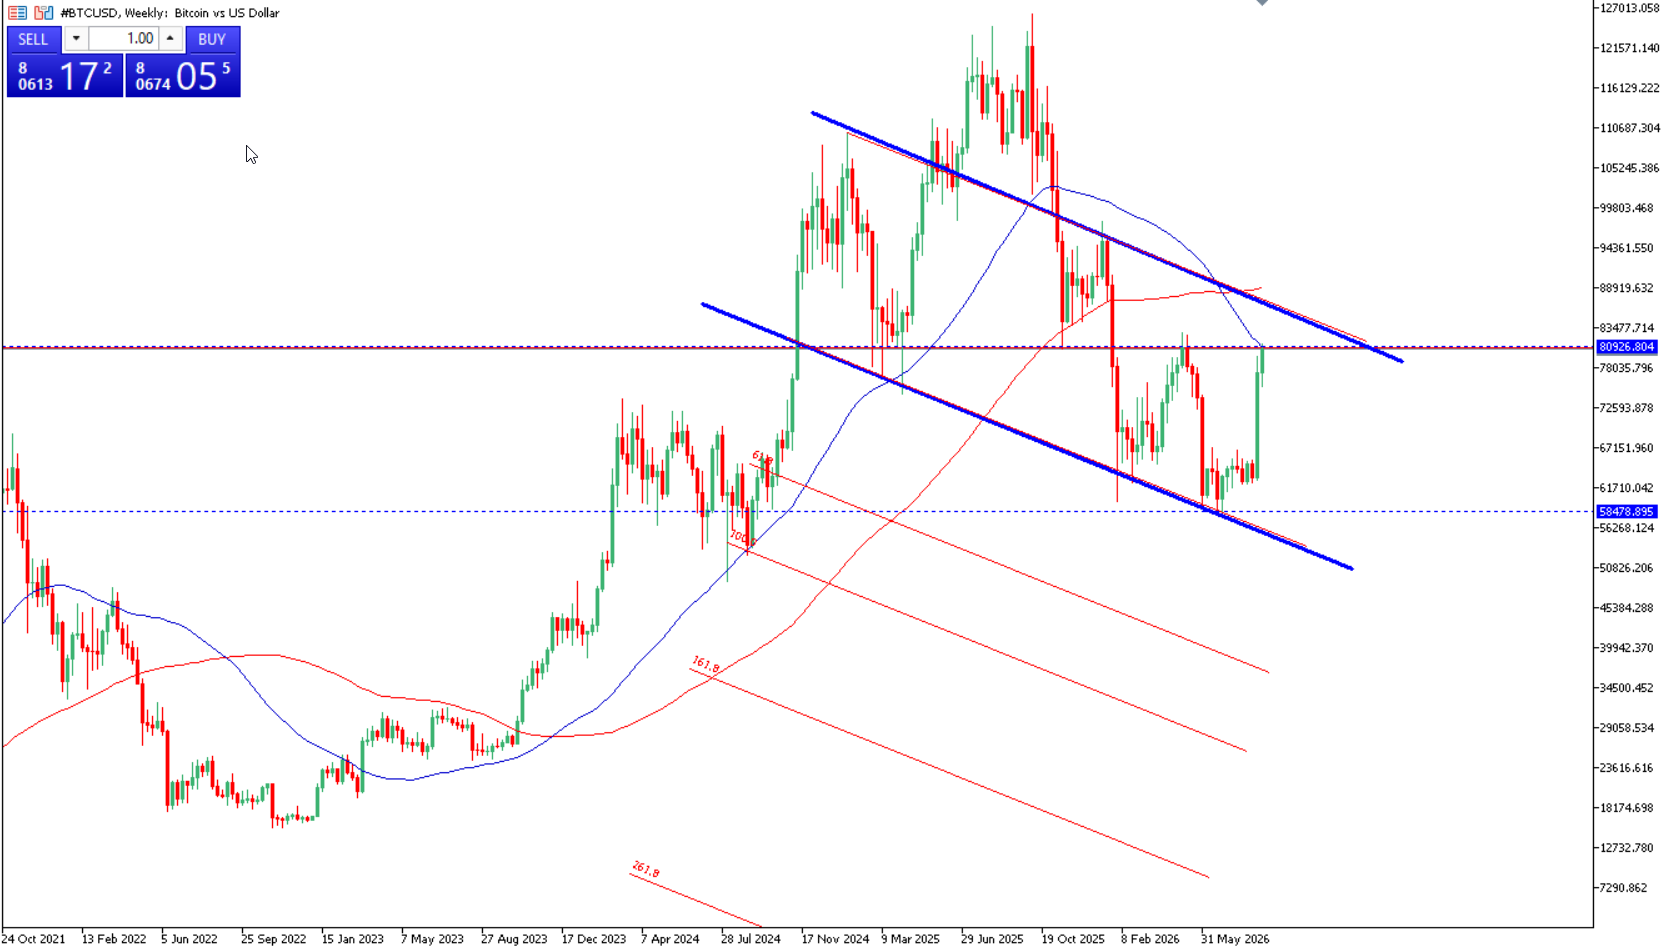
    Bitcoin climbed above $80,000 for the first time since mid-May, extending a strong recovery across the cryptocurrency market. The asset briefly traded above $81,000 and has gained approximately 28% during August.

    Several factors have supported the rally.

    Proposed legislation offering greater regulatory clarity for the US cryptocurrency industry has improved sentiment. At the same time, concerns surrounding US debt, Treasury-market intervention, and the long-term value of the dollar have encouraged renewed interest in alternative assets.

    The US Treasury’s plan to expand purchases of longer-dated bonds has also revived discussion around the ‘debasement trade.’ If government intervention limits the rise in bond yields without resolving underlying debt concerns, some investors may shift capital towards assets perceived as independent of traditional monetary systems.


    Bitcoin has benefited from this narrative alongside Gold, although the cryptocurrency’s stronger momentum has produced a more aggressive price move.

    From a technical perspective, maintaining a position above $80,000 could strengthen bullish momentum and bring the $85,000 region into focus. A more sustained breakout could eventually encourage speculation about a move towards $95,000–$100,000.

    However, after such a rapid monthly advance, Bitcoin may remain vulnerable to profit-taking. A return below $80,000 would suggest that the breakout has lost momentum, while a deeper decline could place attention back on the previous consolidation area.

    Oil Falls Despite Increased Pressure on Iran

    Oil prices extended their decline as traders assessed the latest US measures against Iran.

    Brent crude fell towards $91 per barrel, while West Texas Intermediate traded close to $84. Both benchmarks had already declined by more than 2% during Monday’s session as investors took profits following two weeks of gains.

    The United States has threatened additional economic penalties against countries continuing to conduct business with Iran. However, the market appears to view economic sanctions as a lower immediate threat to physical oil supplies than direct military action.

    This explains why oil prices declined instead of rising following the announcement.

    Nevertheless, the geopolitical risk premium has not disappeared. Iran continues to threaten action against vessels crossing the Strait of Hormuz, a critical route for global energy exports. Reports that a tanker was damaged near Oman also highlighted the continuing threat to regional shipping.

    Oil traders must therefore balance two opposing forces: reduced expectations of an immediate military escalation and the persistent possibility of supply disruption.

    A further decline in Brent could indicate that geopolitical concerns are being priced out of the market. Any confirmed disruption to shipping or oil production, however, could quickly reverse the move.

    Treasury Yields Stabilise as Debt Concerns Remain

    The US 10-year Treasury yield held close to 4.71% after declining by approximately four basis points on Monday.

    Bonds initially found support following reports that the Treasury could use part of its cash reserves to fund purchases of older, higher-yielding securities. Such buybacks may improve market liquidity and reduce pressure on longer-term borrowing costs.

    However, Treasury Secretary Scott Bessent stopped short of announcing further changes to US debt management policy. This left investors questioning whether buybacks can provide more than temporary relief.

    The larger concerns remain the scale of US government borrowing, persistent inflation, and elevated oil prices. Unless these pressures ease, long-term yields could remain high even if Treasury intervention generates short-term demand for bonds.

    For equity traders, the direction of yields remains particularly important. Falling yields may support growth and technology shares by reducing the rate used to value future earnings. Renewed upward pressure could create another obstacle for the NASDAQ and other highly valued areas of the market.

    Gold Struggles to Maintain Earlier Gains

    Gold briefly reached its highest level since May before reversing lower towards $4,640 per ounce.

    The metal has recently benefited from concerns about government debt, possible currency debasement, and instability in the bond market. However, a recovery in the US Dollar and profit-taking limited Tuesday’s advance.

    Gold is currently being influenced by several competing factors. Fiscal uncertainty and geopolitical risks provide support, while elevated Treasury yields increase the opportunity cost of holding a non-yielding asset.

    As a result, the direction of the Dollar and long-term bond yields may remain central to Gold’s next significant move.

    Jackson Hole Places Interest Rates Back in Focus

    Federal Reserve Chair Kevin Warsh is scheduled to speak at the Jackson Hole symposium on Friday. Investors will look for indications of how the central bank intends to respond to stubborn inflation, elevated energy prices, and signs of slower economic growth.

    A more restrictive message could support the Dollar and bond yields while placing pressure on stocks, Gold, and Bitcoin. A more balanced or accommodative tone may provide relief to risk assets, particularly if NVIDIA’s earnings also exceed expectations.

    This creates two major tests for markets during the same week: NVIDIA must reinforce confidence in corporate earnings and the AI trade, while the Federal Reserve must provide greater clarity on the interest rate outlook.

    What Traders Should Watch

    The most important developments over the coming sessions include:

    * NVIDIA’s earnings, guidance, and the reaction across semiconductor stocks
    * Whether the NASDAQ 100 can sustain its recovery
    * Bitcoin’s ability to remain above $80,000
    * Changes in US Treasury yields and the Dollar
    * Brent crude’s response to developments involving Iran and the Strait of Hormuz
    * Gold’s ability to attract demand despite elevated yields
    * Kevin Warsh’s comments on inflation and interest rates at Jackson Hole

    Market sentiment has improved, but the recovery remains fragile. With technology earnings, monetary policy, and geopolitical risks converging, traders should prepare for higher volatility and potential reversals across multiple asset classes.

    Always trade with strict risk management. Your capital is the single most important aspect of your trading business.

    Please note that times displayed based on local time zone and are from time of writing this report.

    Click HERE to access the full HFM Economic calendar.

    Want to learn to trade and analyse the markets? Join our webinars and get analysis and trading ideas combined with better understanding of how markets work. Click HERE to register for FREE!

    Click HERE to READ more Market news.

    Andria Pichidi
    HFMarkets


    Disclaimer: This material is provided as a general marketing communication for information purposes only and does not constitute an independent investment research. Nothing in this communication contains, or should be considered as containing, an investment advice or an investment recommendation or a solicitation for the purpose of buying or selling of any financial instrument. All information provided is gathered from reputable sources and any information containing an indication of past performance is not a guarantee or reliable indicator of future performance. Users acknowledge that any investment in Leveraged Products is characterized by a certain degree of uncertainty and that any investment of this nature involves a high level of risk for which the users are solely responsible and liable. We assume no liability for any loss arising from any investment made based on the information provided in this communication. This communication must not be reproduced or further distributed without our prior written permission.

  4. #84
    Junior Member HFblogNews's Avatar
    Join Date
    Nov 2021
    Posts
    99
    Date: 26th August 2026.

    Oman-Iran Talks Pressure Oil Prices, but Many Investors Remain Unpersuaded.


    Trading Leveraged products is Risky

    Crude oil prices continue to fall for a third day as hopes for the Strait of Hormuz reopening rise. At the same time, economic sanctions placed on Iran are weaker than originally feared, and US inventories rise supporting further downward price movement.

    Nonetheless, investors continue to remain sceptical over a long-lasting peace deal. For this reason, the possibility of crude oil’s bearish trend losing steam remains. Key factors influencing price volatility are the Core PCE Price Index, GDP, and speeches at the Jackson Hole symposium later in the week.

    US-Iran Tensions Influencing Oil Markets

    Iran and Oman have agreed on the outline of a temporary navigation corridor through the Strait of Hormuz. According to reports, this plan includes a joint mine-clearing and further technical talks on shipping security. However, the Strait has not fully reopened yet, and vessel traffic remains well below normal levels. The development has still reduced some of the geopolitical risk premium in oil markets, though major risks remain.

    The US has announced secondary sanctions on Iran and its trading partners. Treasury Secretary Scott Bessent said restrictions will target individuals, vessels, and companies involved in buying Iranian oil or supporting its nuclear and missile programmes. At the same time, President Trump said no talks with Iran are planned, increasing fears of renewed conflict.

    Foreign Secretary Marco Rubio, has told European allies that the attacks have ‘stopped for now’. This also follows what most analysts believe: that the Strait will remain partially closed and tensions are likely to rise again. However, traders cannot be certain when tensions will again rise, affecting oil prices.

    Crude Oil Impact - Core PCE Price Index and Prelim GDP

    The US Dollar and interest rates can play an important role in the pricing of crude oil. For today’s US data, markets are expecting Core PCE inflation to rise by around 0.2% month-on-month, with the annual rate around 3.2-3.3%. Meanwhile, the Q2 GDP second estimate is expected to be revised to 1.5%

    For the Dollar, Core PCE is likely to be the more important release for traders. This is because it is the Federal Reserve’s preferred inflation indicator. A reading above expectations would increase pressure on the Fed to consider higher rates, potentially pushing Treasury yields and the Dollar higher. If the GDP data also rise, the possibility of a rate hike increases substantially. A reading below expectations would reduce rate-hike expectations and could weaken the Dollar.

    A more expensive Dollar and expectations of an interest rate hike can pressure oil prices, while a weaker Dollar may support crude oil

    Crude Oil - Technical Analysis


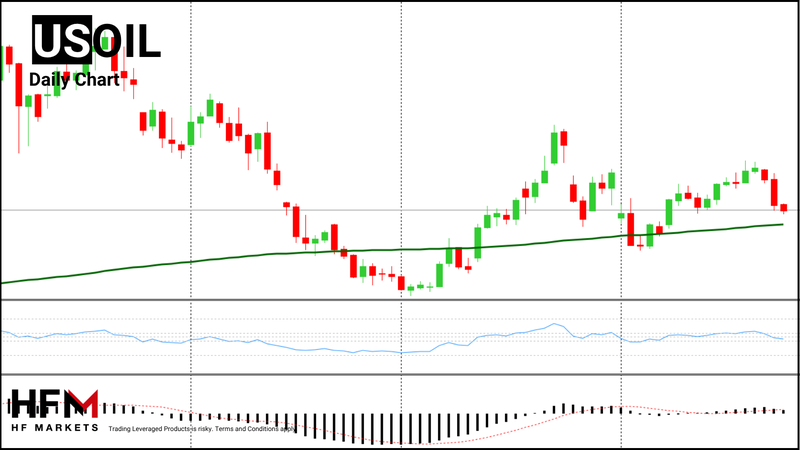
    HFM - Crude Oil Daily Chart

    WTI is trading close to $80 after falling sharply from weekly highs, with the short-term technical bias turning bearish. The price has broken below the $82 support area and is trading below its key moving averages, while the MACD remains negative. The RSI is around 34, showing strong selling pressure but also suggesting that the market is getting closer to oversold conditions.

    Medium-term timeframes are also indicating downward price movement, however, the support level at $78.60 is a risk for sellers. If the price remains below the 200-bar moving average, at $81.25 on the 5-minute timeframe, sell signals may remain active.

    Key Takeaways:

    * Oil continues to decline as hopes rise for a partial reopening of the Strait of Hormuz. US sanctions proving less severe than feared, and higher US inventories also support lower oil prices.
    * Geopolitical risk remains high, as traders expect US-Iran tensions could quickly escalate in the future, potentially limiting further declines.
    * Core PCE and GDP are key upcoming catalysts: stronger US data could support the Dollar and rate-hike expectations, adding pressure on oil, while weaker data could support prices.
    * WTI remains technically bearish near $80, trading below key moving averages, although support around $78.60 may limit further downside.

    Always trade with strict risk management. Your capital is the single most important aspect of your trading business.

    Please note that times displayed based on local time zone and are from time of writing this report.

    Click HERE to access the full HFM Economic calendar.

    Want to learn to trade and analyse the markets? Join our webinars and get analysis and trading ideas combined with better understanding of how markets work. Click HERE to register for FREE!

    Click HERE to READ more Market news.

    Michalis Efthymiou
    HFMarkets


    Disclaimer: This material is provided as a general marketing communication for information purposes only and does not constitute an independent investment research. Nothing in this communication contains, or should be considered as containing, an investment advice or an investment recommendation or a solicitation for the purpose of buying or selling of any financial instrument. All information provided is gathered from reputable sources and any information containing an indication of past performance is not a guarantee or reliable indicator of future performance. Users acknowledge that any investment in Leveraged Products is characterized by a certain degree of uncertainty and that any investment of this nature involves a high level of risk for which the users are solely responsible and liable. We assume no liability for any loss arising from any investment made based on the information provided in this communication. This communication must not be reproduced or further distributed without our prior written permission.

  5. #85
    Junior Member HFblogNews's Avatar
    Join Date
    Nov 2021
    Posts
    99
    Date: 31st August 2026.

    Jackson Hole Hawks and New Middle East Clashes.


    Trading Leveraged products is Risky

    The US and Iran exchanged fire for the first time since July, quickly driving oil prices back above $85 per barrel. According to reports, the US struck rocket launchers on Larak Island, located near the key Strait of Hormuz chokepoint.

    Market sentiment had been improving over the previous week as oil fell below $80 and NVIDIA’s earnings report beat expectations. Economists also continued to expect the Federal Reserve to pause in September. However, as crude oil prices have remained above $80 per barrel for three weeks, hopes for a pause are weakening.

    Jackson Hole - Warsh Increases the Hawkish Tone

    Other than the geopolitical developments, US monetary policy is particularly interesting and is triggering volatility among US Dollar pairs. The Fed Chair’s speech on 28 August was significantly more hawkish than most analysts were expecting.

    According to Mr Warsh, inflation remains too high, while the economy continues to show resilience. July PCE inflation was running at 3.7% year-on-year, and Warsh said recent data had not convinced him that underlying inflation pressures were improving sufficiently. At the same time, he described economic activity as strong, supported by stable labour markets, solid business investment, and healthy corporate profits. This gives the Fed less reason to tolerate persistent inflation out of concern that tighter policy could push the economy into recession.

    The Chair said credit and lending markets showed few signs that current monetary policy was restraining the economy. This was particularly important because it suggests the current 3.50%-3.75% Federal Funds Rate might not be restrictive enough. Economists view this as an indication that interest rates need to rise in order for inflation to come down.

    US-Iran Clashes Push Oil Prices Higher

    US forces struck two Iranian rocket launchers on Larak Island, near the Strait of Hormuz. US officials said Revolutionary Guard forces were preparing to launch rockets carrying sea mines into the key shipping route.

    Iran reported casualties from the attack and subsequently retaliated by launching ballistic missiles towards US bases in Jordan. Reports indicated that nearly all incoming missiles were intercepted, with no significant impact. The confrontation is increasing concerns over further escalation and potential disruption to shipping.

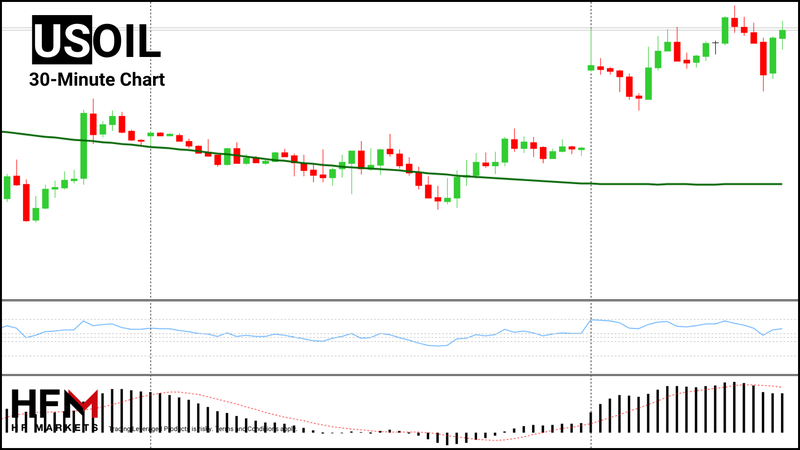
    Crude Oil - Back Above $86!

    Crude oil opened with a bullish price gap measuring 1.70%. The price thereafter rose even further above $86, but has since lost momentum. However, even with the retracement, the price is maintaining a bullish price indication. The price is remaining above the trendline and moving average. However, the price is slightly below the VWAP, though this may indicate the possibility of entering at a competitive price. While the price on the 5-minute timeframe remains above the 200-bar simple moving average, buy signals are likely to remain intact.


    HFM - Crude Oil 30-Minute Chart

    US Dollar - US Dollar Finds Support But Retraces

    The US Dollar is the worst-performing currency of the day as it loses some of last week’s gains. However, the currency is the best-performing of the past week. The Dollar found support from the hawkish tone of the Federal Reserve, lower risk sentiment, and higher oil prices.

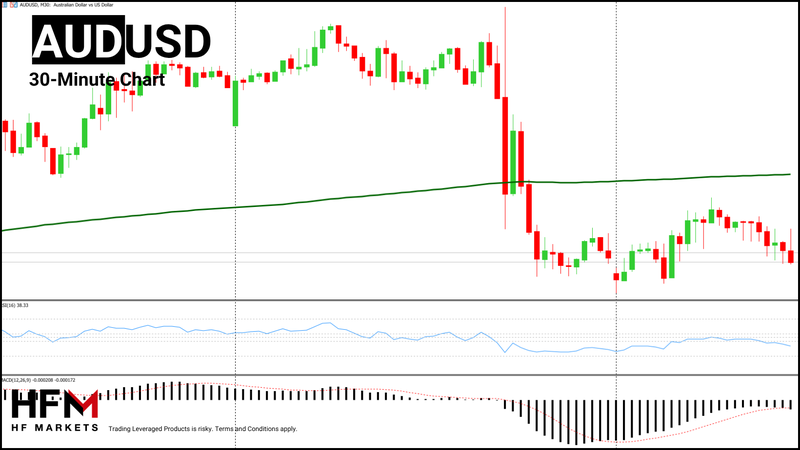
    At the start of the European session, the best-performing currencies are the Japanese Yen, Swiss Franc and the Euro. For this reason, traders wishing to trade a weakening Dollar may opt for the EUR/USD, USD/CHF and USD/JPY. The worst-performing currencies are the Australian Dollar and the British Pound.

    A key factor for the US Dollar will be price volatility in the oil markets and this week’s employment data. If crude oil remains above $85 per barrel and NFP data beats expectations, the US Dollar may rise back to 100.00. However, the US Dollar is currently continuing to retrace lower so far.


    HFM - AUDUSD 30-Minute Chart

    Key Takeaways:

    * US-Iran tensions have escalated again following the first direct exchange of strikes since July.
    * Crude Oil has moved back above $85 per barrel, increasing concerns over potential supply disruptions through the Strait of Hormuz.
    * Fed Chair Kevin Warsh adopted a more hawkish tone at Jackson Hole, stressing that inflation remains too high.
    * Higher interest rate expectations have provided support to the US Dollar, despite the current retracement.
    * This week’s US employment data, particularly NFP, will be a key driver of Fed expectations and market volatility.

    Always trade with strict risk management. Your capital is the single most important aspect of your trading business.

    Please note that times displayed based on local time zone and are from time of writing this report.

    Click HERE to access the full HFM Economic calendar.

    Want to learn to trade and analyse the markets? Join our webinars and get analysis and trading ideas combined with better understanding of how markets work. Click HERE to register for FREE!

    Click HERE to READ more Market news.

    Michalis Efthymiou
    HFMarkets


    Disclaimer: This material is provided as a general marketing communication for information purposes only and does not constitute an independent investment research. Nothing in this communication contains, or should be considered as containing, an investment advice or an investment recommendation or a solicitation for the purpose of buying or selling of any financial instrument. All information provided is gathered from reputable sources and any information containing an indication of past performance is not a guarantee or reliable indicator of future performance. Users acknowledge that any investment in Leveraged Products is characterized by a certain degree of uncertainty and that any investment of this nature involves a high level of risk for which the users are solely responsible and liable. We assume no liability for any loss arising from any investment made based on the information provided in this communication. This communication must not be reproduced or further distributed without our prior written permission.

  6. #86
    Junior Member HFblogNews's Avatar
    Join Date
    Nov 2021
    Posts
    99
    Date: 2nd September 2026.

    Oil Breaks $90 as Gold and NASDAQ Face Growing Pressure.


    Trading Leveraged products is Risky

    On Tuesday, the trend from Monday continued with bond yields rising to a new high and oil prices breaking above $90 per barrel. In addition, investors are increasingly pricing in the possibility of a Fed interest rate hike later this month. As a result, the stock market and Gold came under pressure, while the US Dollar maintained support.

    The underlying driving factor remains oil prices and the Middle East crisis. Tensions in the Middle East continue to escalate, with further attacks on two tankers. Higher oil prices are prompting inflation fears, which in effect are pushing yields and interest rates higher. According to the Chicago exchange, almost 70% of the market is pricing in a September hike.

    Oil Prices and the Middle East Conflict

    The US launched a new round of strikes against Iran on 1 September, targeting Islamic Revolutionary Guard Corps (IRGC) military infrastructure around the Strait of Hormuz, including air-defence systems, radar, communications, and capabilities used to threaten shipping. Washington said the operation was a response to recent Iranian attempts to attack commercial vessels and US forces in the region.

    Tensions intensified further after two oil supertankers carrying Saudi crude were struck by projectiles while attempting to exit the Strait of Hormuz. The Saudi-operated Sidr and the Senegal Prosperity were hit within minutes of each other, with each tanker carrying around two million barrels of crude oil.

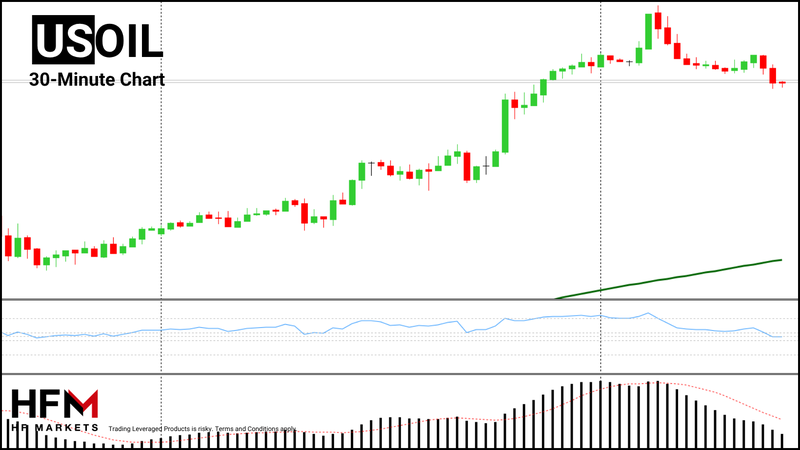
    Crude oil prices rose throughout all sessions on Monday, with few attempts to retrace lower. The price also rose during this morning’s Asian session, but has since lost momentum. The higher oil prices are supporting the US Dollar Index, which is now close to breaking above 100.00.

    Even though the bullish momentum weakened this morning, the price remains firmly above the key moving averages. In addition to this, the bearish correction has also not continued to decline to a lower low. For this reason, the price is not switching to a bearish indication. If the price breaks again above $91.30, the asset is likely to see stronger bullish indications materialise.


    HFM - Crude Oil 30-Minute Chart

    Gold Under Pressure With $4,000 as a Potential Target

    Gold has now fully corrected the bullish impulse wave seen in the second half of August. The downward momentum is due to the rise in oil prices, a stronger US Dollar, and expectations of interest rate hikes. However, for Gold more needs to be taken into account.

    Under the current market conditions of higher inflation and interest rates, Gold can potentially continue to decline. For example, key support levels can be seen at $4,000. However, if bond yields, which continue to rise, trigger a market shock, investors are likely to turn to Gold, which is not related to the US government. For this reason, traders need to consider the possibility of a decline as well as a rebound.

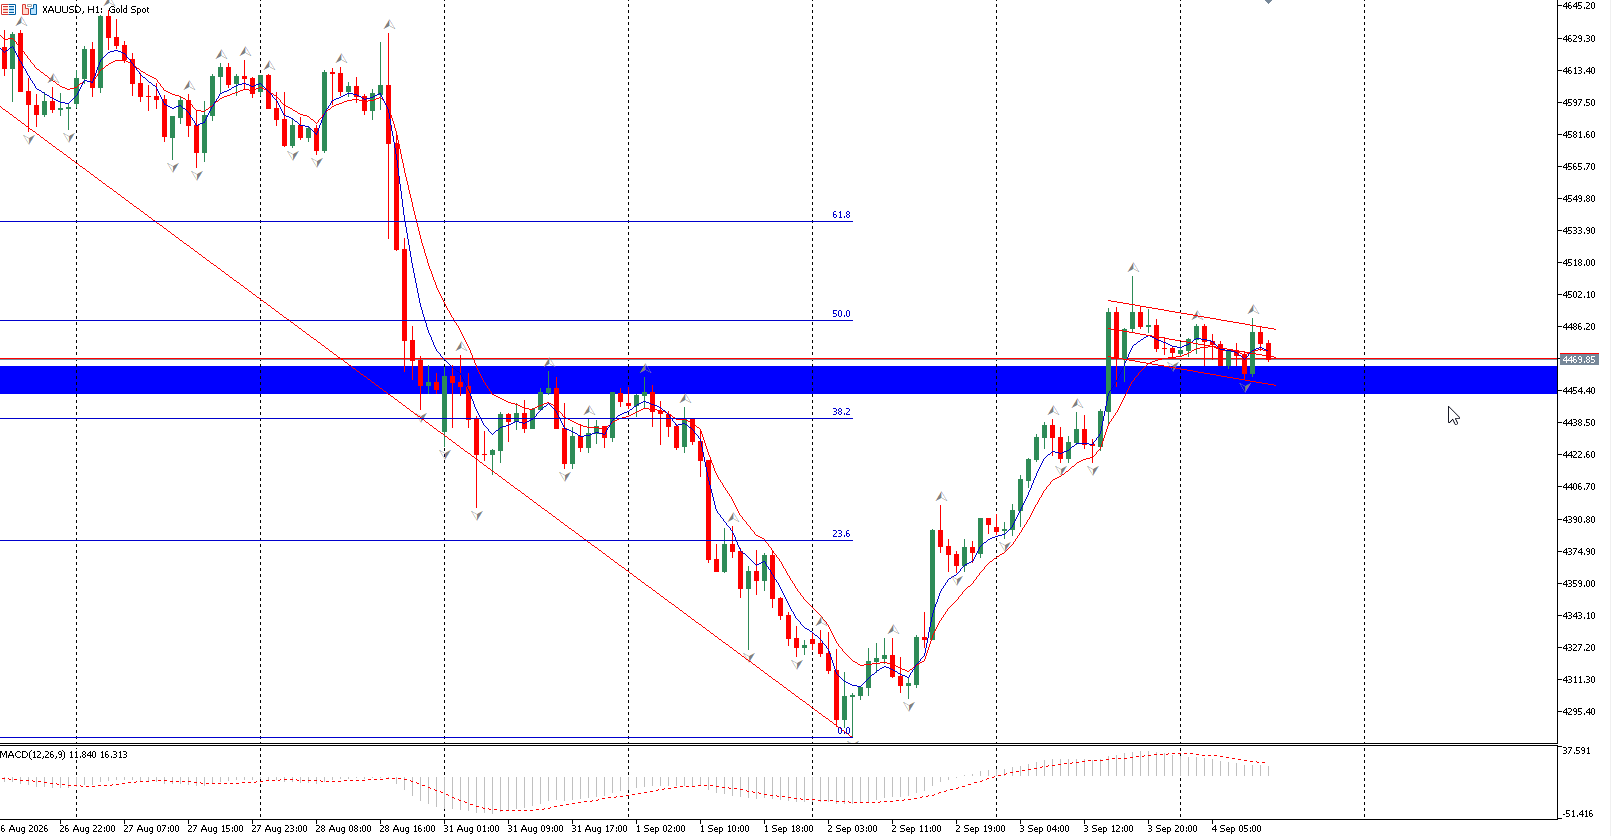
    For the time being, the price in the short and medium term continues to provide a bearish bias. Gold continues to show bearish indications in the short term, with downside pressure intact while the price stays below the $4,400–$4,450 resistance area. The price trades below the moving average and VWAP, but trades in a neutral area on the RSI and MACD.

    For the medium term, the outlook is more neutral. A recovery above $4,500 would improve the bullish structure and could bring $4,700 back into focus, while a sustained break below $4,300 would signal a deeper correction back down to $4,000.


    HFM - Gold 30-Minute Chart

    NASDAQ Hit By Low Risk Sentiment

    The bearish pressure on the stock market is clear, with only positive earnings and the AI trend keeping stocks afloat. The NASDAQ has fallen as inflation and interest rates hit consumer sentiment, while geopolitics prompt a risk-off appetite.

    None of the global indices is trading higher on Tuesday, which gives a bearish bias. The VIX index provides a neutral indication, while the put-call ratio is again on the rise, indicating selling pressure. 86% of the most influential NASDAQ stocks fell on Monday.

    A key source of support for the NASDAQ came from Apple, its third-largest constituent, which rose 2.60%. According to analysts, without Apple’s gains, the index would likely have fallen below its previous support levels and seen a larger decline.

    A key support level for the NASDAQ is $28,889.20. In the short term, bearish signals from moving averages are likely to remain unless the price increases above $29,090.

    Key Takeaways:

    * Oil breaks above $90 as US-Iran tensions escalate and two oil supertankers are struck near the Strait of Hormuz.
    * Bond yields continue to rise, while markets increasingly price in the possibility of a Fed rate hike later this month.
    * Gold remains under pressure, with $4,000 emerging as a potential downside target if the bearish trend continues.
    * NASDAQ sentiment remains bearish, although Apple’s 2.60% gain helped prevent a deeper decline.
    * The US Dollar remains supported by higher yields, rising oil prices, and expectations of tighter Fed policy.

    Always trade with strict risk management. Your capital is the single most important aspect of your trading business.

    Please note that times displayed based on local time zone and are from time of writing this report.

    Click HERE to access the full HFM Economic calendar.

    Want to learn to trade and analyse the markets? Join our webinars and get analysis and trading ideas combined with better understanding of how markets work. Click HERE to register for FREE!

    Click HERE to READ more Market news.

    Michalis Efthymiou
    HFMarkets


    Disclaimer: This material is provided as a general marketing communication for information purposes only and does not constitute an independent investment research. Nothing in this communication contains, or should be considered as containing, an investment advice or an investment recommendation or a solicitation for the purpose of buying or selling of any financial instrument. All information provided is gathered from reputable sources and any information containing an indication of past performance is not a guarantee or reliable indicator of future performance. Users acknowledge that any investment in Leveraged Products is characterized by a certain degree of uncertainty and that any investment of this nature involves a high level of risk for which the users are solely responsible and liable. We assume no liability for any loss arising from any investment made based on the information provided in this communication. This communication must not be reproduced or further distributed without our prior written permission.

  7. #87
    Junior Member HFblogNews's Avatar
    Join Date
    Nov 2021
    Posts
    99
    Date: 4th September 2026.

    Waller's Dovish Pivot Keeps the Dollar on the Back Foot Into Payrolls.


    Trading Leveraged products is Risky

    Risk assets extended their advance overnight as traders further pared back the odds of a September Fed hike following dovish remarks from Governor Christopher Waller. The Dollar sits near multi-month lows, the Yen is having its best week since the July intervention, and havens like Gold are holding firm even as oil grinds higher on Middle East supply risk. All eyes now turn to today’s payrolls report to settle the debate.

    USD: Payrolls Need to Shock to Change the Story

    The Dollar’s slide has further to run unless today’s jobs report delivers a genuine upside surprise. Governor Waller told a Reuters NEXT event that he could support holding rates steady this month if incoming data confirms the disinflation trend already underway, a notable break from Chair Kevin Warsh's hawkish tone last week. He pointed to the Fed's preferred inflation gauge, core PCE, cooling to 3.7% in July from 4.1% in May, as evidence the trend is intact, and added that he doesn't expect payrolls to deviate much from the recent trend of a stable but unspectacular labour market.

    Markets have listened. Pricing for a 25-basis-point September hike has fallen to roughly a coin flip, down sharply from the high 60s just a couple of days ago, and a broad Dollar index is trading at its softest levels since May. Consensus looks for around 56,000 jobs after last month’s shock decline, with unemployment seen steady at 4.1%, a number the Fed still reads as close to full employment. A print in line with or below consensus should keep the Dollar offered into the weekend; only a genuinely hot number is likely to revive hike bets meaningfully, given the Fed's stated focus is now squarely on the inflation side of its mandate rather than labour slack.

    Treasuries have caught a bid alongside the Dollar’s weakness. Two-year yields are holding near 4.33%, off their 20-month highs, while the curve has bull-steepened as the front end outperforms. Ten- and 30-year yields have also eased modestly, though longer-dated paper remains hostage to inflation and fiscal-supply concerns that a single jobs report won't resolve.

    JPY: Best Week Since the Intervention, but the Move May Be Maturing

    The Yen has been the standout story this week, rallying as much as 2% in a single session and putting it on track for its strongest week since Japan and the US jointly intervened to arrest its slide. USD/JPY has pulled back from a low near 155.30 to trade around 156.30 as some of the move gets pared, but the underlying driver, rapidly rising conviction in a Bank of Japan hike this month, remains intact. Swaps now imply roughly a 75% chance of a September move, with an increase fully priced by October, and speculation is building that policymakers could even deliver back-to-back hikes or a larger single step.

    Speculation that Japan’s pension giants, including the GPIF, may lean further into domestic bonds has also helped anchor the long end of the JGB curve, with super-long-term yields easing even as global yields stay elevated. That combination, a more hawkish BoJ and firmer demand for domestic duration, is a supportive backdrop for the Yen, though positioning is less stretched than during prior Yen squeezes, which argues for consolidation rather than an immediate extension towards the 150-152 area.

    Commodities: Oil's Geopolitical Bid, Gold Steady

    Brent crude is holding just above $95.50 per barrel and is on track for its biggest weekly gain since July, driven by renewed US-Iran tensions and fears of prolonged disruption to flows through the Strait of Hormuz. That geopolitical premium is one of the few forces working against the broader disinflation narrative the Fed is trying to build a case around. Gold, meanwhile, is consolidating near $4,470 per ounce after a 2% overnight rally, on course to finish the week roughly flat, a sign that havens are being supported more by real-yield declines than by any fresh flight-to-safety impulse.


    Risk Sentiment: Equities Extend Gains, Asia Leads

    The broader risk backdrop remains constructive. Wall Street’s rally on Waller's comments carried into Asia, where the regional equity gauge climbed around 1%, China's blue chips jumped 4%, and South Korea’s KOSPI rose 2%; Japan’s Nikkei 225 added 1.4% on the day but is still nursing a weekly loss of nearly 2% given the Yen's surge. Nasdaq and S&P futures point to a firmer US open, and European equities are set to open modestly higher too. Strategists caution that the picture is still finely balanced: with roughly two weeks to the Fed decision and mid-term elections looming, several see the risks to sentiment as skewed slightly to the downside from here, arguing for a degree of caution even as markets chase the dovish narrative.

    What to Watch

    Today’s US non-farm payrolls report (consensus 56,000, unemployment 4.1%) is the clear focus. A soft or in-line print should reinforce the Dollar-negative, Yen-positive, risk-on setup currently in place; a strong beat would revive September hike pricing quickly, given how far it has already fallen this week, and could trigger a sharper reversal in both rates and FX than the market is currently positioned for.

    Always trade with strict risk management. Your capital is the single most important aspect of your trading business.

    Please note that times displayed based on local time zone and are from time of writing this report.

    Click HERE to access the full HFM Economic calendar.

    Want to learn to trade and analyse the markets? Join our webinars and get analysis and trading ideas combined with better understanding of how markets work. Click HERE to register for FREE!

    Click HERE to READ more Market news.

    Andria Pichidi
    HFMarkets


    Disclaimer: This material is provided as a general marketing communication for information purposes only and does not constitute an independent investment research. Nothing in this communication contains, or should be considered as containing, an investment advice or an investment recommendation or a solicitation for the purpose of buying or selling of any financial instrument. All information provided is gathered from reputable sources and any information containing an indication of past performance is not a guarantee or reliable indicator of future performance. Users acknowledge that any investment in Leveraged Products is characterized by a certain degree of uncertainty and that any investment of this nature involves a high level of risk for which the users are solely responsible and liable. We assume no liability for any loss arising from any investment made based on the information provided in this communication. This communication must not be reproduced or further distributed without our prior written permission.

  8. #88
    Junior Member HFblogNews's Avatar
    Join Date
    Nov 2021
    Posts
    99
    Date: 7th September 2026.

    NFP Shocks Markets as Fed, ECB, and Middle East Risks Take Focus.


    Trading Leveraged products is Risky

    Strong US employment data makes an interest rate hike almost certain, pressuring Gold, certain stocks, and supporting the Dollar. At the same time, Middle East tensions continue to rise as Iran and the US target tankers. Lastly, Germany, the largest European economy, has seen its far-right party win in regional elections.

    The US will witness lower order flow due to today’s bank holiday. Nonetheless, the market is still likely to witness high volatility as investors price in recent developments. In addition to this, investors will now turn their attention to the upcoming European Central Bank rate decision, US producer inflation, and consumer inflation.

    German Election, European Central Bank and the Euro

    The Euro is trading slightly higher during this morning’s Asian session, but this is a minor bullish bias. Investors are attempting to remain calm as local elections continue to indicate a switch towards the far right. According to economists, far-right governments do not necessarily mean a negative impact on the Euro, but instability would. For example, if governments are unable to form in Germany, Italy, and Spain, similar to France, the Euro could come under pressure.

    Nonetheless, for now, the far-right win in Germany is not negatively impacting the Euro. In fact, the Euro is finding some support from expectations that the European Central Bank will increase rates on Thursday. Markets expect the ECB to increase its main refinancing rate from 2.40% to 2.65%. This would take the ECB’s rate to an 18-month high.

    The EUR this morning is performing particularly well against the NZD, but as the NZD is the worst-performing of the day so far, traders should be cautious of a correction. Currently, the EUR/NZD is above the 200-bar moving average on the 5-minute chart and is above the VWAP. However, the RSI is trading in the negative zone, which again may indicate a correction. If the price rises above 1.97770, bullish signals can remain. If the price falls below the 1.97543 support level, indications will turn bearish.

    Gold and NFP

    The latest US non-farm payrolls report showed a much stronger-than-expected employment sector. The release was the largest surprise since April 2026, with the economy adding 162,000 jobs in August, almost three times the market forecast of around 56,000.

    Meanwhile, the unemployment rate remained unchanged at 4.1%. The labour force participation rate rose to 61.6%, providing further evidence that labour market conditions remain relatively resilient. According to economists, there is now very little reason for the Federal Reserve not to hike interest rates. Now, 60% of investors believe the Federal Reserve will hike on 16 September.

    The stronger employment data strengthened expectations that the Federal Reserve could raise interest rates at its September meeting, particularly as policymakers continue to monitor elevated inflation.

    Following the report, US Treasury yields and the Dollar moved higher, while Gold came under pressure, as markets increased their probability of a September rate hike. Attention now shifts to the upcoming US inflation data, which could be decisive for the Fed’s next move.

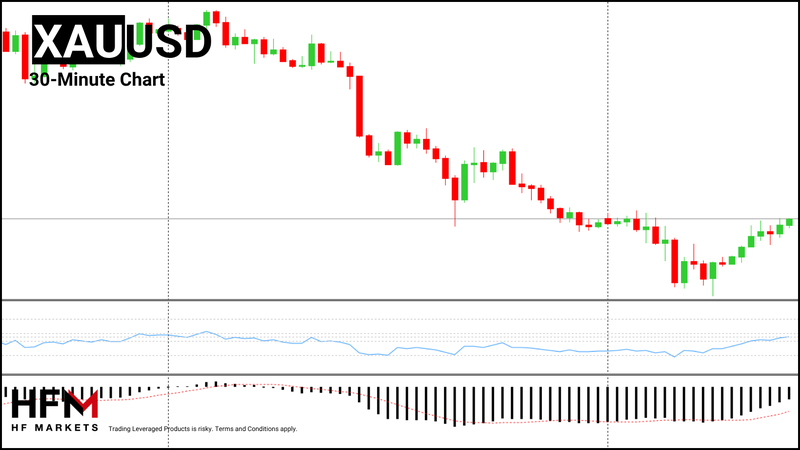
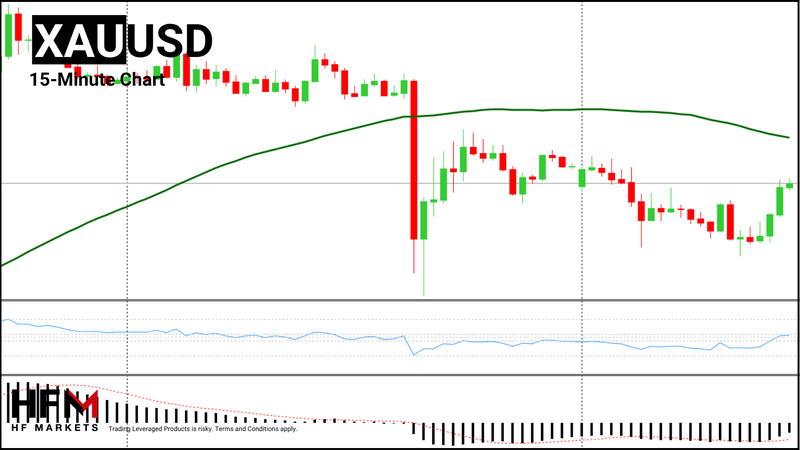
    Gold came under instant pressure after the release, falling 2.40% in a period of 45 minutes. However, Gold has not maintained its bearish momentum, but still retains its bearish bias on certain timeframes, such as the 30-minute chart. On the 5-minute timeframe, the price is attempting to break above the 200-bar moving average. If the price breaks above this level at $4,418.50, bullish signals may materialise.


    HFM - Gold 30-Minute Chart

    A positive factor for Gold is that the US Dollar Index is trading lower this morning. However, traders should note that certain price movements may be due to low order flow because of the US bank holiday.

    Crude Oil - Middle East Tensions Rise

    The US-Iran conflict escalated further over the weekend as Iran said it targeted three oil tankers in the Strait of Hormuz, describing the attacks as retaliation for US strikes on Iranian vessels. The US had earlier hit three Iranian crude carriers after American warships came under ballistic missile attack.

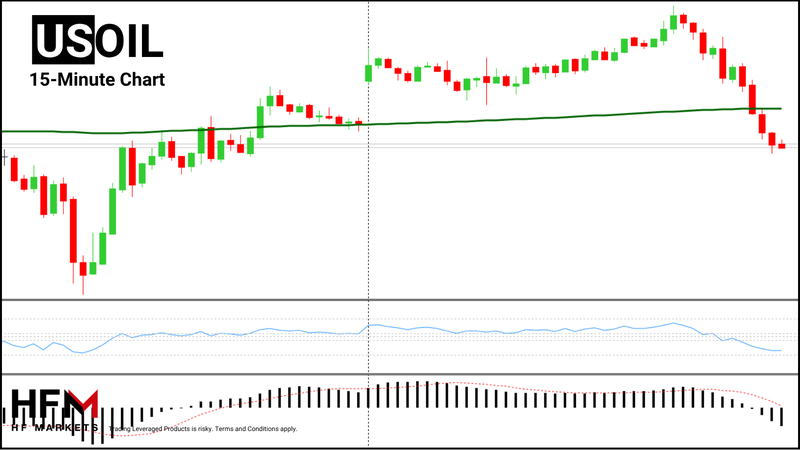
    The latest developments have sharply increased risks to energy flows through the Strait of Hormuz. This has pushed oil prices higher and raised concerns over prolonged supply disruptions from the Middle East. Crude oil prices came close to reaching a new monthly high but have found resistance. This comes as Iran says negotiations with Oman are progressing positively despite the weekend’s developments.


    HFM - Crude Oil 15-Minute Chart

    Key Takeaways:

    * Strong NFP boosts Fed hike expectations: The US added 162,000 jobs in August, well above forecasts, increasing expectations for a September rate hike.
    * Gold remains under pressure: Gold fell sharply following the NFP release as Treasury yields and the US Dollar strengthened, although some recovery attempts have emerged.
    * Oil supported by Middle East tensions: Escalating US-Iran tensions and attacks involving oil tankers have increased concerns over potential supply disruptions through the Strait of Hormuz.
    * ECB and European politics in focus: The Euro remains supported by expectations of an ECB rate hike, while Germany’s regional election results add further political uncertainty for investors.

    Always trade with strict risk management. Your capital is the single most important aspect of your trading business.

    Please note that times displayed based on local time zone and are from time of writing this report.

    Click HERE to access the full HFM Economic calendar.

    Want to learn to trade and analyse the markets? Join our webinars and get analysis and trading ideas combined with better understanding of how markets work. Click HERE to register for FREE!

    Click HERE to READ more Market news.

    Michalis Efthymiou
    HFMarkets


    Disclaimer: This material is provided as a general marketing communication for information purposes only and does not constitute an independent investment research. Nothing in this communication contains, or should be considered as containing, an investment advice or an investment recommendation or a solicitation for the purpose of buying or selling of any financial instrument. All information provided is gathered from reputable sources and any information containing an indication of past performance is not a guarantee or reliable indicator of future performance. Users acknowledge that any investment in Leveraged Products is characterized by a certain degree of uncertainty and that any investment of this nature involves a high level of risk for which the users are solely responsible and liable. We assume no liability for any loss arising from any investment made based on the information provided in this communication. This communication must not be reproduced or further distributed without our prior written permission.

  9. #89
    Junior Member HFblogNews's Avatar
    Join Date
    Nov 2021
    Posts
    99
    Date: 8th September 2026.

    Japanese Yen Hits February High as BoJ Rate-Hike Expectations Rise.


    Trading Leveraged products is Risky

    The Japanese Yen continues to increase in value, rising to its highest level since February. The rise in value is due to expectations of a more hawkish Bank of Japan and currency intervention. According to the Japanese government, as well as many institutions on Wall Street, this price movement is different and may not simply lose momentum like previous interventions.

    BoJ - Two Rate Hikes on the Table

    Many economists believe the recent strengthening of the Japanese Yen could be different from previous moves. One key reason is the prospect of further tightening from the Bank of Japan. While even the more hawkish forecasts generally point to quarterly rather than back-to-back rate hikes, expectations are building that the BoJ could raise rates again before the end of the year.

    Prime Minister Takaichi’s economic adviser, Takuji Aida, recently indicated that he expects a September rate hike followed by quarterly increases. Most economists do not expect consecutive hikes. Nevertheless, a second hike before year-end remains a possibility.

    This creates the potential for the BoJ to tighten monetary policy at a faster pace than the Federal Reserve over the medium term. As a result, the Japanese Yen has continued to strengthen across the currency market, while USD/JPY has come under increasing downward pressure.

    Bruce Kasman, JPMorgan’s global head of economics, said that the bank forecasts two adjustments before year-end. Markets themselves are pricing in roughly a 60% chance of another move by December after the expected September hike. Bank of America also backs two hikes, with its economists advising quarterly hikes, including September and December 2026. According to reports, its foreign exchange team has also turned bullish on the Japanese yen for the rest of 2026.

    Higher Exchange Rate to OffSet Higher Oil Prices

    Japan is extremely exposed to imported energy. More than 90% of Japan’s crude oil imports come from the Middle East. The government also stated earlier that roughly 93% of its crude imports normally pass through the Strait of Hormuz. For this reason, it is vital for the government and Bank of Japan to boost the currency in order to purchase energy products more easily.

    Governor Ueda has specifically identified the weak Yen and geopolitical developments in the Middle East as factors that could increase inflation risks. These risks will be considered when deciding whether to raise interest rates further. If the Bank of Japan adjusts rates from 1.00% to 1.50% by 2027, it would take the rate to the highest level since 1995.

    GBP/JPY and CHF/JPY


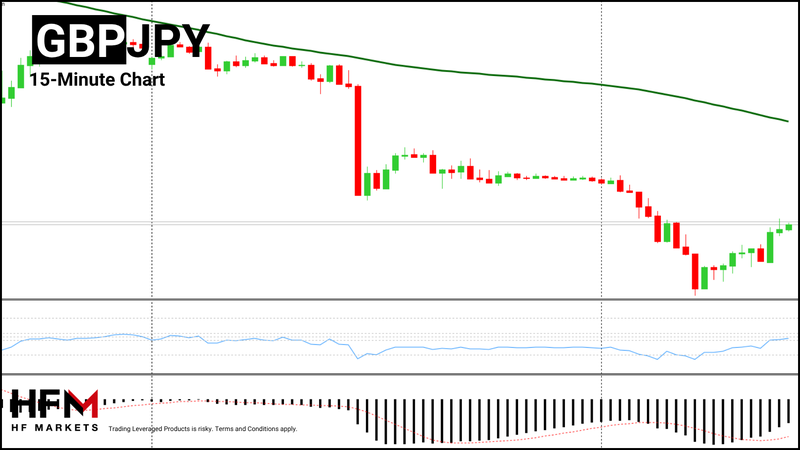
    HFM - GBPJPY 30-Minute Chart

    Even though the USD/JPY is one of the most popular assets to be traded, other currency pairs are also interesting. Investors should note that the Federal Reserve is also looking to hike interest rates, and it's a safe haven currency. For this reason, at times, the US Dollar may also experience strong gains. The US Dollar is the second-best-performing currency this year after the Australian Dollar. By contrast, the Swiss Franc and British Pound are among the weakest-performing currencies of 2026 so far.

    The GBP/JPY is trading lower this morning falling particularly in the first half of the Asian session. The pair is currently rated ‘Strong Sell’ on the 30-minute, hourly, 4-hour, and daily timeframes. However, on smaller timeframes, traders are cautious of the retracement that is forming. The RSI is not indicating an oversold price due to the retracement, while the MACD remains negative.

    Importantly, the price remains below the 20, 50, 100, and 200-period moving averages. The price is trading at a key support level from earlier in the year, but if the price drops again below 207.383, sell indications remain.

    The CHF/JPY is witnessing a similar condition to the GBP/JPY but is experiencing stronger bearish momentum. However, on larger timeframes, CHF/JPY is witnessing an oversold indication on the RSI.

    Key Takeaways:

    * The Japanese Yen has strengthened to its highest level since February.
    * Expectations are increasing for further Bank of Japan rate hikes before year-end.
    * Higher oil prices are adding to inflation risks and increasing the importance of a stronger Yen.
    * GBP/JPY and CHF/JPY remain under downward pressure as the Yen continues to strengthen.

    Always trade with strict risk management. Your capital is the single most important aspect of your trading business.

    Please note that times displayed based on local time zone and are from time of writing this report.

    Click HERE to access the full HFM Economic calendar.

    Want to learn to trade and analyse the markets? Join our webinars and get analysis and trading ideas combined with better understanding of how markets work. Click HERE to register for FREE!

    Click HERE to READ more Market news.

    Michalis Efthymiou
    HFMarkets


    Disclaimer: This material is provided as a general marketing communication for information purposes only and does not constitute an independent investment research. Nothing in this communication contains, or should be considered as containing, an investment advice or an investment recommendation or a solicitation for the purpose of buying or selling of any financial instrument. All information provided is gathered from reputable sources and any information containing an indication of past performance is not a guarantee or reliable indicator of future performance. Users acknowledge that any investment in Leveraged Products is characterized by a certain degree of uncertainty and that any investment of this nature involves a high level of risk for which the users are solely responsible and liable. We assume no liability for any loss arising from any investment made based on the information provided in this communication. This communication must not be reproduced or further distributed without our prior written permission.

  10. #90
    Junior Member HFblogNews's Avatar
    Join Date
    Nov 2021
    Posts
    99
    Date: 10th September 2026.

    ECB Rate Decision and US PPI: EUR/USD Outlook.


    Trading Leveraged products is Risky

    The Euro edges higher on Thursday as the European Central Bank’s rate decision edges closer. Markets expect the ECB to increase interest rates from 2.40% to 2.65% taking the main refinancing rate to an 18-month high. The Euro will be influenced by the rate decision, but also largely from the guidance given during the press conference. However, the US Producer Price Index may also impact the Euro, as the Dollar is its main competitor.

    Later this afternoon, the US will announce its Producer Price Index (producer inflation), followed by the consumer inflation figure tomorrow. If the US inflation is higher than expectated and the ECB’s President, Christine Lagarde, is not hawkish enough, the Euro may decline. Currently, the worst-performing currency of the day is the US Dollar. The Euro is the third-best-performing after the Swiss Franc and New Zealand Dollar.

    Euro and the ECB Rate Decision

    The 25-basis-point hike is fully priced into the Euro and European indices. For this reason, a rate hike is not adequate to maintain bullish price movement. The key for investors will be Christine Lagarde’s comments on future rate hikes and inflation in the EU.

    Eurozone headline inflation jumped from 2.9% to 3.3% in August, largely because of energy prices. At the same time, Brent crude has moved back above $100, increasing the risk that energy inflation spreads into transportation, manufacturing, and eventually consumer prices.

    If President Lagarde indicates that today's hike may not be enough, markets will start pricing the deposit rate at 2.75%. Deutsche Bank, JPMorgan, and BNP Paribas are among those now expecting another 25-basis-point hike in December. This would be positive for the Euro and negative for European indices.

    Interestingly, the ECB may raise its 2026 growth projection because the economy has performed better than expected. Stronger growth gives the ECB more room to hike without fearing an immediate recession or economic slowdown. As the EU is a net importer of oil, higher oil prices are also key to the Eurozone’s monetary policy.

    From recent speeches and interviews, certain ECB members are looking to vote for a hike. These include Germany’s Joachim Nagel, as well as Isabel Schnabel and Olli Rehn. However, others are more reluctant, such as Philip Lane. Though it is vital that traders remember that developments across the Atlantic will also be key for the Euro.

    US Dollar and US Inflation

    Producer inflation figures can be just as important for the Fed’s decision as the CPI. For this reason, many traders are eagerly watching today’s event. Traders should note that last month’s PPI announcement prompted double the amount of volatility compared with CPI.

    Currently, there is roughly a 60% probability of a 25-basis-point Fed hike, while economists surveyed by Reuters still mostly expect the Fed to leave the 3.50-3.75% rate unchanged. That disagreement means that today’s inflation figure will be even more important and could trigger new impulse waves.

    Analysts expect the Producer Price Index to have risen 0.4% in August and the core figure to have risen 0.3%. If the figure reads higher than the expected, the US Dollar could rise and the Euro could decline. Tomorrow’s CPI figure could also have a similar impact but may experience slightly less volatility.


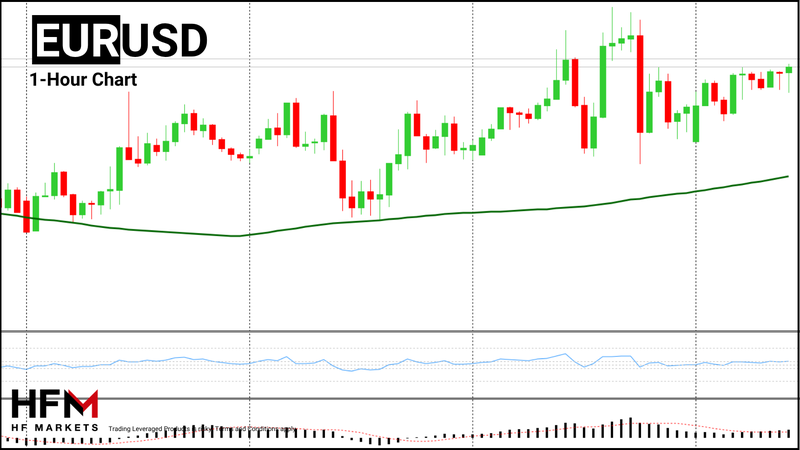
    HFM - EURUSD 1-Hour Chart
    In terms of technical analysis, the Euro has a slight edge over the US Dollar for the time being. The price is trading above the key moving averages on most timeframes, but is also at a neutral level on the RSI. During the Asian session, the price of the EUR/USD rose but is now trading sideways. Investors are most likely awaiting for the latest data to be made public.

    If the price rises above 1.16405, buy signals could start to materialise from the breakout and bullish crossover. However, traders should be cautious of the resistance levels at 1.16535 and 1.16795. However, if the PPI release pushes the price down, with a weaker PPI reading, sell signals may potentially materialise at 1.16340 and 1.16290.

    Key Takeaways:

    * The ECB is expected to hike rates by 25 basis points, but Lagarde’s guidance on future hikes will be more important for the Euro.
    * Higher Eurozone inflation and rising oil prices could strengthen the case for further ECB tightening later this year.
    * US PPI and CPI will be key for Fed expectations, with stronger-than-expected inflation likely to support the US Dollar.
    * EUR/USD remains technically supported, with 1.16405 as a key upside trigger and resistance around 1.16535–1.16795.

    Always trade with strict risk management. Your capital is the single most important aspect of your trading business.

    Please note that times displayed based on local time zone and are from time of writing this report.

    Click HERE to access the full HFM Economic calendar.

    Want to learn to trade and analyse the markets? Join our webinars and get analysis and trading ideas combined with better understanding of how markets work. Click HERE to register for FREE!

    Click HERE to READ more Market news.

    Michalis Efthymiou
    HFMarkets


    Disclaimer: This material is provided as a general marketing communication for information purposes only and does not constitute an independent investment research. Nothing in this communication contains, or should be considered as containing, an investment advice or an investment recommendation or a solicitation for the purpose of buying or selling of any financial instrument. All information provided is gathered from reputable sources and any information containing an indication of past performance is not a guarantee or reliable indicator of future performance. Users acknowledge that any investment in Leveraged Products is characterized by a certain degree of uncertainty and that any investment of this nature involves a high level of risk for which the users are solely responsible and liable. We assume no liability for any loss arising from any investment made based on the information provided in this communication. This communication must not be reproduced or further distributed without our prior written permission.

Page 9 of 10 FirstFirst ... 7 8 9 10 LastLast

Bookmarks

Posting Permissions

  • You may not post new threads
  • You may not post replies
  • You may not post attachments
  • You may not edit your posts
  •